Memory Inventory Days and Stock Price Lead-Lag: The 2026 Signal
Memory inventories and memory stocks rarely turn at the same moment. A share price can recover while reported inventory remains elevated, or weaken while manufacturers are still announcing strong sales. That apparent contradiction is often the most useful part of the signal: financial markets price expectations, while quarterly accounts describe conditions that have already developed.
In 2026, the relationship deserves particular attention because DDR5 server memory, NAND flash, and enterprise storage are following increasingly differentiated demand patterns. A company-wide inventory figure can conceal tightness in one product and accumulated stock in another.
The analytical priority is direction, interpreted in context. Are inventories becoming easier to sell? Are customers consuming products rather than merely replenishing warehouses? Are prices improving faster or slower than investors expected? Inventory days can help answer those questions, but they are not a mechanical trading rule.
What Inventory Days Actually Measure
Inventory days estimate how long the recorded inventory would support activity at a stated cost-of-sales rate. A common calculation divides average inventory by cost of goods sold and multiplies the result by the number of days in the period.
Some companies present a metric using ending inventory instead. That difference matters when inventory changes rapidly during a quarter.
The measure also includes more than finished products ready for shipment. Depending on the business and reporting structure, raw materials and work in process contribute to the balance.
For an analyst, comparability is therefore the first requirement. A supplier’s company-wide inventory days should not be compared directly with a customer’s finished-memory buffer or a distributor’s weeks of stock without identifying the boundaries.
Why a Rising Inventory Balance Can Accompany Improving Conditions
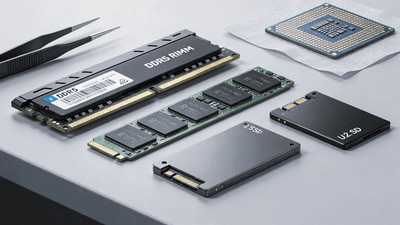
Inventory is reported in money, not simply in bits. Manufacturing costs, product mix, and the stage of processing can affect the balance even when physical demand is strong.
A company expanding production can hold more work in process. A technology transition can require planned build-ahead inventory. Conversely, a declining inventory balance can reflect write-downs or production cuts rather than healthy consumption.
Micron’s fiscal Q2 2026 commentary offered a useful example: ending inventory increased by $62 million sequentially to $8.3 billion, while inventory days stood at 123. Management separately described DRAM inventory days as below 120 and especially tight. The monetary increase alone did not capture the product-level interpretation.
The practical lesson is to examine the reason for the change before assigning it a bullish or bearish label.
The Denominator Can Change the Signal
Inventory days depend on both inventory and cost of goods sold. A change in either can move the ratio.
If shipments expand, the cost-of-sales denominator can rise and reduce inventory days even when inventory value stays relatively stable. If production costs fall through a technology transition, the relationship can change again.
This creates a common interpretive trap: assuming that every decline in inventory days represents an equivalent reduction in physical stock.
A stronger analysis reviews inventory value, the reported days metric, shipment trends, and management’s explanation together. Where available, physical or product-specific commentary adds another perspective. The ratio is useful because it compresses information—but compression also hides detail.
Stocks Anticipate the Accounting Turn
A share price reflects expectations about future earnings, cash flow, and risk. Reported inventory describes a balance measured at a particular date and disclosed afterward.
That timing difference helps explain why stocks can move before inventory normalizes. Investors may expect production discipline, improving customer consumption, or stronger contract pricing to reduce future oversupply.
The opposite can happen near a cycle peak. Stocks may weaken while current margins remain strong because investors anticipate slower price increases or additional supply.
However, there is no universal lead interval. The relationship can change with valuation, interest rates, product exposure, and the surprise contained in new information. A claim that memory shares consistently lead inventory by a fixed number of months requires an explicit historical test.
The Relevant Signal Is Often the Second Derivative
Markets react not only to whether conditions are improving, but to whether they are improving faster than expected.
Inventory days can fall while a stock declines if investors had anticipated a larger reduction. Prices can rise while shares weaken if the increase is smaller than the prevailing earnings assumptions.
From a portfolio manager’s perspective, this is the difference between a strong business condition and a positive surprise. They are not the same thing.
The useful questions therefore include the pace of inventory normalization, the pace of price improvement, and the changes in earnings expectations. A favorable trend can already be reflected in valuation by the time it becomes obvious in quarterly results.
DDR5 Needs Its Own Demand Framework
DDR5 serves different applications, including servers and client systems. Those markets should not be treated as one undifferentiated demand pool.
Server configurations can differ significantly in memory capacity, module type, and qualification requirements. A manufacturer’s available DRAM bits are not automatically interchangeable with every customer’s preferred DDR5 module.
Micron’s 2026 commentary identified strong data-center demand across DDR5, low-power memory, and HBM. That supports the need to examine conventional server memory alongside stacked memory rather than treating AI demand as an HBM-only phenomenon.
For investors, the key distinction is product exposure. A company benefiting from qualified server products can experience different inventory conditions from a business concentrated in more price-sensitive client applications.
HBM Influences the DDR5 Supply Discussion
HBM and DDR5 meet different requirements, but manufacturers allocate capital and production resources across their memory portfolios. That makes the relationship relevant to supply planning.
Strong demand for one product can affect investment priorities without creating a simple one-for-one reduction in another. Technology, yields, packaging requirements, and production arrangements all influence the outcome.
Analysts should therefore avoid fixed conversion rules unless they are supported by a defined manufacturing basis.
The more useful approach tracks capacity allocation, customer commitments, and qualified output. It asks whether additional DDR5 supply can reach the applications where demand is strongest, rather than assuming that aggregate DRAM growth answers every availability question.
NAND Requires a Separate Inventory Interpretation
NAND flash supports enterprise SSDs, client SSDs, mobile storage, and other products. Demand and inventory can differ across those channels.
A producer can experience strong enterprise orders while customers in another segment maintain adequate stock. Company-wide NAND commentary may therefore conceal important product-mix differences.
Technology transitions add complexity because they can change bit output, cost, and qualification schedules. More bits produced do not necessarily mean that every finished-storage product is available immediately.
For an analyst, the relevant chain runs from wafer output to qualified NAND components, controller and firmware integration, finished drives, and customer deployment. Inventory pressure can emerge at any point along that chain.
Enterprise Storage Connects Components with Systems
An enterprise SSD is not merely a quantity of NAND in a package. It combines flash with controllers, firmware, interfaces, and customer qualification.
That changes how inventory should be read. Available NAND does not establish immediate availability of the exact drive a server or storage customer requires.
Enterprise demand also reflects deployment schedules. A customer can order ahead of installation, hold drives while preparing infrastructure, or consume existing inventory without placing proportionate new orders.
From a storage supplier’s perspective, visibility improves when qualified products move into repeat deployment. From an investor’s perspective, the challenge is to distinguish component tightness, finished-drive availability, and genuine end-user consumption.
AI Expands Storage Demand Beyond Model Training
AI-related storage needs include datasets, checkpoints, retrieval systems, and selected applications that move data between memory and storage tiers.
Micron’s fiscal Q2 commentary identified vector databases and key-value-cache offload among the applications supporting data-center NAND demand. It also described growing SSD participation in capacity-storage tiers. These are specific demand pathways, not proof that every NAND product benefits equally.
The investment implication is a broader enterprise-storage opportunity. The operational implication is continued differentiation by performance, capacity, qualification, and workload.
A strong demand narrative still needs to be reconciled with actual shipments, customer inventories, and supplier output. Technological relevance does not eliminate the possibility of purchasing ahead of consumption.
Restocking and Consumption Can Look Similar at First
Both restocking and sustained demand can increase supplier shipments. The difference appears in what happens afterward.
If customers are filling depleted buffers, orders may normalize once target inventory is restored. If end consumption is expanding, purchases can remain strong without creating an excessive downstream stockpile.
One quarter rarely settles the distinction. Analysts need repeated observations of supplier shipments, customer stocks, pricing, and deployment activity.
For a procurement manager, rebuilding inventory can be entirely rational when availability is uncertain. For an investor, that rational behavior still needs interpretation because it can temporarily make upstream demand appear stronger than final consumption.
Pricing Helps Confirm—or Challenge—the Inventory Signal
Inventory trends become more informative when combined with pricing. Falling stocks and stronger realized prices can support a tightening interpretation, while rising inventory and weakening prices can suggest pressure.
But spot prices, contract prices, and a company’s reported average selling price are different measures. Their timing and product composition can vary.
A supplier’s average price can improve because its mix shifts toward higher-value products, even if comparable-product pricing changes less dramatically.
The appropriate comparison uses consistent categories. DDR5 server contracts, client memory, enterprise SSDs, and raw NAND indications should not be treated as one interchangeable price series.
Build a Dashboard, Not a Single-Number Rule
A useful 2026 monitoring framework combines several dimensions:
- Supplier inventory value and reported inventory days.
- Product-level commentary on DRAM and NAND availability.
- Customer and channel inventory where comparable information exists.
- Realized pricing and contract-price direction by application.
- Shipment growth, production plans, and technology transitions.
- Changes in earnings expectations and stock valuation.
The objective is agreement among signals. When several measures point toward durable tightening, the interpretation is stronger. When they conflict, the discrepancy deserves investigation rather than being averaged away.
Testing Lead and Lag Requires Clean Data
A quantitative study should use the dates when inventory information became public, not simply the fiscal quarter-end dates. Investors cannot trade on financial data before it is disclosed.
It should also define returns, adjust for corporate actions, and distinguish company-specific performance from broader market movements.
Different lag windows can be tested, but the analysis should avoid selecting only the interval that produces the most attractive result. Relationships should be checked across cycles and, where possible, outside the period used to develop the model.
Without that work, the lead-lag story remains a plausible framework rather than a verified predictive rule. Historical correlation also does not establish that inventory changes independently caused the share-price movement.
Three Ways to Read the 2026 Signal
A constructive scenario combines improving product availability discipline, sustained enterprise demand, and earnings upgrades that remain supported by operating evidence.
A concentrated scenario features strong DDR5 server or enterprise SSD demand alongside more balanced conditions elsewhere. Aggregate inventory becomes less useful than product-specific information.
A cautionary scenario emerges when customer purchasing runs ahead of deployment, price improvement slows, or supplier output expands faster than expected.
These are analytical scenarios, not forecasts with assigned probabilities. Their value is to identify what evidence would support or challenge a thesis before the stock price makes the answer appear obvious.
Low Inventory Is Not Automatically a Buy Signal
Very tight inventory can support pricing, but it can also coincide with optimistic earnings expectations and demanding valuations. The market may already have anticipated the benefit.
Likewise, high inventory can be uncomfortable while creating the conditions for a future recovery if production adjusts and customer consumption improves.
The investment question is therefore relative: what is changing compared with expectations, and what is already reflected in the share price?
That requires company-specific analysis of product mix, supply response, margins, and valuation. Inventory days are one input into that judgment, not a substitute for it.
The Signal Lies in the Connection
The 2026 memory cycle is best understood through the interaction of supplier inventories, customer behavior, DDR5 demand, NAND production, and enterprise-storage deployment.
Stocks can lead the reported operating turn because they anticipate it. They can also move in the opposite direction when expectations become too aggressive.
The strongest analysis connects inventory trends with pricing and earnings revisions while keeping product categories distinct. The useful signal is not a magic number of days. It is evidence that the next change in operating conditions is different from the one the market already expects.